Interest rates do not affect only companies that borrow money. They influence how much consumers spend, whether businesses invest, how suppliers finance their operations and how attractive saving becomes. This means a debt-free company can still experience the effects of higher rates through weaker customer demand, higher supplier costs or slower economic activity. The Bank of England explains that higher interest rates make borrowing more expensive and saving more attractive, which tends to reduce spending by households and businesses. (Bank of England)
Customers May Have Less Money to Spend
Higher mortgage and loan payments can reduce disposable income. A household that previously paid £1,200 per month on its mortgage but later pays £1,450 has £250 less available each month for restaurants, clothing, entertainment, home improvements or other purchases.
A business may therefore experience weaker sales even if it has no debt itself. The effect can be particularly important for companies selling discretionary products and services because customers can postpone or cancel those purchases more easily than essential spending.
Higher Rates Can Change Investment Decisions
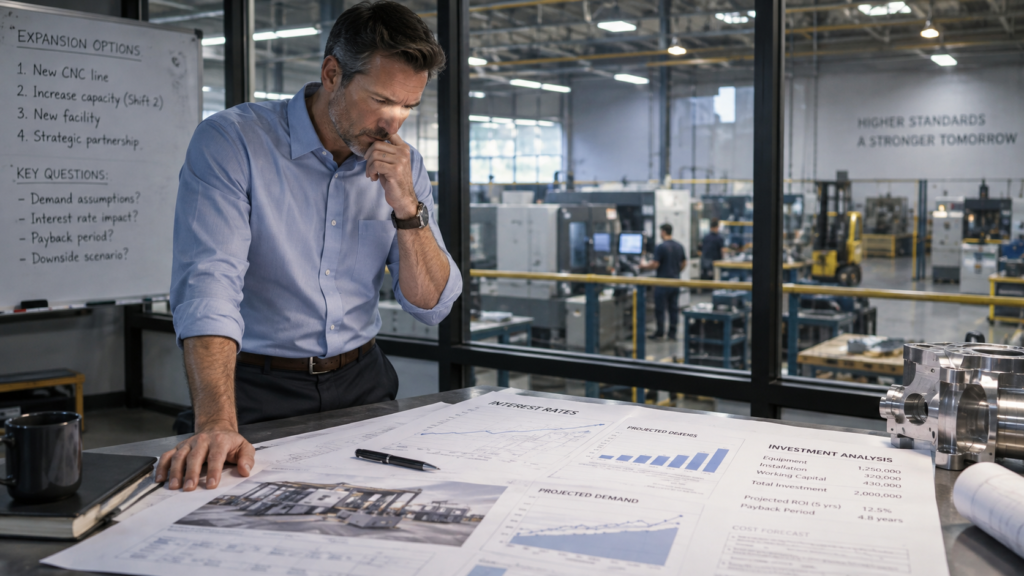
Interest rates also affect the cost of expanding a business. New machinery, another warehouse, additional vehicles or a new location may still be commercially attractive, but higher financing costs reduce the expected return and can make management more cautious.
Current UK data shows the effect clearly. In July 2026, the effective interest rate on new bank loans to UK SMEs was 6.61%, up from 6.36% in June. The Bank of England also reported that higher borrowing costs and uncertainty were weighing on business investment intentions. (Bank of England)
Example: A £100,000 Investment
A company considers investing £100,000 in new equipment. Management expects demand to increase by 15%, based on recent sales, market trends and customer interest. If demand develops as expected, the additional capacity may generate a strong return and the decision could prove highly successful.
If demand weakens, financing remains expensive or market conditions change, the same investment may generate a much lower return. The decision was not necessarily irrational; the outcome simply depended partly on events that management could estimate but could not control.
Business Decisions Are Made Under Uncertainty
Businesses usually understand that major investments involve risk. Decisions are often based on realistic assumptions about demand, expected sales, market growth, operating costs and financing. The difficulty is that even well-researched assumptions are still assumptions about the future.
A company may correctly identify an opportunity and still receive a disappointing result because economic conditions change after the decision is made. Equally, a risky expansion can perform much better than expected if demand increases strongly.
This is why a good business decision can still produce a poor outcome, while a risky decision can sometimes succeed. Forecasting, scenario planning and sensitivity analysis can reduce uncertainty, but they cannot eliminate it. Management is making a calculated decision, not predicting the future with certainty.
Suppliers Can Pass Higher Costs On
A business can also be affected through its supply chain. A supplier may use finance to buy inventory, operate vehicles or invest in machinery. If its financing costs increase, part of that additional expense may eventually appear in the prices charged to customers.
This creates indirect exposure. A company may have no borrowing at all but still pay more because businesses around it depend on finance. The relevant question is therefore not only “Does our company have debt?” but also “How financially exposed are our customers and suppliers?”
Higher Rates Can Slow Hiring and Expansion
When demand becomes less predictable and investment becomes more expensive, businesses may delay recruitment, expansion or major purchases. The Bank of England reported in July 2026 that business investment was expected to soften as higher borrowing costs and weaker confidence affected investment intentions. (Bank of England)
That does not mean every business should stop investing when rates are high. An opportunity with strong expected returns may still justify the cost. The important point is that the hurdle becomes higher: management needs greater confidence that the expected return compensates for the additional cost and risk.
Lower Interest Rates Can Work in the Opposite Direction
When interest rates fall, borrowing can become cheaper, mortgage costs may eventually fall and saving becomes relatively less attractive. Households may have more capacity to spend, while some investments that previously looked too expensive can become commercially viable.
However, lower rates do not automatically create growth. Demand, confidence, competition and wider economic conditions still matter. Interest rates influence decisions; they do not determine every outcome.
What Should Businesses Actually Watch?
Management should look beyond the headline interest rate and monitor what is happening to customer spending, financing costs, supplier prices, investment returns and demand forecasts. Different businesses will respond differently: a furniture retailer may be highly exposed to households postponing large purchases, while an essential professional service may see much less change.
Interest rates are therefore important because they influence the environment in which business decisions are made. A company does not need a loan to be affected. Its customers, suppliers and competitors may have one, and their reactions can eventually appear in its sales, costs and growth opportunities.
The key question is not simply “Are interest rates high or low?” It is “How do current rates change the risk and expected return of the decisions this business is considering?”
Category: Business Strategy
Secondary category: Business Theory
Sources
Bank of England — What Is Happening With Interest Rates in the UK? and What Are Interest Rates? Explains how rates influence borrowing, saving and spending by households and companies. (Bank of England)
Bank of England — Monetary Policy Report, July 2026. Covers business investment, confidence and the impact of higher financing costs. (Bank of England)
Bank of England — Money and Credit, July 2026. Reports lending activity and effective interest rates on new lending to UK businesses and SMEs. (Bank of England)